Renaissance Capital Increases Dangote Refinery Share Value to ₦700
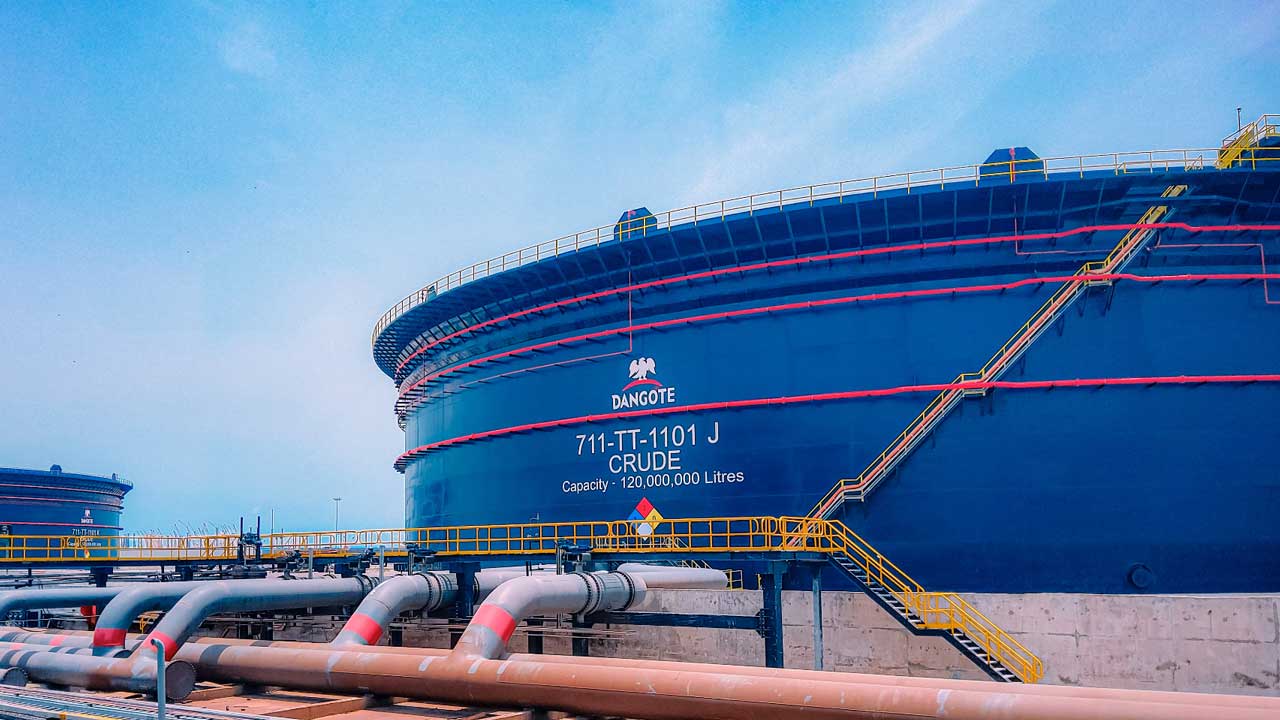
Renaissance Capital has increased Dangote Refinery's share value to ₦700.41, citing strong revenue and profit growth in 2026 as key factors.
Renaissance Capital Africa has increased its valuation of Dangote Petroleum Refinery and Petrochemicals FZE by 33.4 percent, now valuing it at ₦700.41 per share. This is up from the initial public offering (IPO) price of ₦525 per share.
On Sunday, the investment bank released a statement explaining that this increase reflects the refinery’s strong performance in the first nine months of 2026.
“Revenue, EBITDA and net profit all exceeded the firm’s expectations during the period,” the statement said.
In its update on 16 October, titled “Stronger Refining Margins Drive Earnings Outperformance,” Renaissance Capital Africa pointed out that strong refining margins and better operating results are the main reasons for the new valuation.
The new valuation comes as more investors show interest in the refinery after its impressive operational and financial results. Last week, PREMIUM TIMES shared that the refinery made a net profit of $4.7 billion in the first nine months of 2026. This is a big change from a net loss of $117.2 million in the same period of 2025, based on its latest unaudited results.
“Revenue grew by 144 percent from $9.2 billion, while EBITDA increased nearly nine-fold to $5.5 billion from $627.6 million. Operating cash flow rose more than ten-fold to $3.68 billion, showing the refinery’s growing ability to generate significant earnings and cash flow from its operations,” the statement said.
From January to September, the refinery improved its balance sheet. It moved from a net debt position of $1.73 billion in September 2025 to a net cash position of $651 million.
Renaissance Capital Africa stated that this change shows improved liquidity and stronger financial health.
Analysts Raise Concerns
The new valuation is different from what some analysts think. They believe that the current share price of ₦525 per share is too high, given the uncertainties around the refinery’s expansion plans and how long it can maintain its current refining margins.
Razaq Fatai, director of research and advisory at consultancy firm Vestance, reacted to Renaissance Capital Africa’s valuation. He called the refinery’s financial turnaround significant but warned that the higher valuation could mislead retail investors.
“Recording a profit in H1 2026 after a loss in 2025 is no small achievement. But a valuation that lands well above the ₦525 offer price risks giving retail investors false hope. It reads as a margin of safety when it is mostly a bet on outcomes that have not happened yet,” he said.
Mr. Fatai doubted the assumptions behind the valuation, especially concerning the refinery’s planned capacity increase. He mentioned that much of the forecast relies on the refinery doubling its capacity to 1.4 million barrels per day by 2029. This project is expected to cost around $14 billion.
He added that the expansion could face many challenges, such as crude supply limits, foreign exchange issues, high financing costs, and delays that often come with big industrial projects.
“In a DCF, every year of delay erodes value, and Rencap’s own team acknowledges that expansion timing affects the valuation. Treating Phase 2 as near-certain moves future capacity into today’s price,” he said.
A discounted cash flow (DCF) valuation calculates a company’s worth by estimating its future cash flows and adjusting them to their present value.
Mr. Fatai also expressed doubts about the sustainability of the refinery’s current margins. He said the disruptions from the US war against Iran have created unusually favorable conditions for selling jet fuel and diesel in markets facing supply shortages.
He noted that Renaissance Capital Africa expects the refinery’s gross refining margins to rise to $27.50 per barrel in 2026, up from $24 per barrel in the first half of the year.
“These are crisis-level crack spreads, not a steady state,” he said. He warned that margins could fall if the conflict calms down and global refining output returns to normal.
Mr. Fatai added that the same geopolitical issues that are pushing product margins higher could also increase crude procurement and shipping costs. This could expose the refinery to more supply risks.
“If a temporary windfall is extrapolated into terminal value, future cash flows will be overstated,” he said.
He also advised investors to think about the possible limitations of the research reports from the firms involved in the share offer.
He pointed out that Renaissance Capital, Chapel Hill Denham, and CardinalStone are joint issuing houses for the offer. He suggested that investors compare their evaluations with independent assessments.
He mentioned an assessment by GTI Capital, which reportedly values the refinery at around ₦493 per share and says the offer price is fully valued.
Mr. Fatai said the refinery could be a strong business, but it may not be a good investment at its current price.
He encouraged investors to test the valuation against three scenarios: a return to normal refining margins, delays to the planned expansion, and a weaker naira.
Investors should not rely only on optimistic fair-value estimates based on the best assumptions.
Comments
No comments yet.